Profit Focus
The headlines have been blowing up with venture capitalist’s ominous warnings about the need for profitability. It’s a little bit ironic to me, since after all the point of a business is to make money. Nobody invests in a business for it to forever lose money. According to financial theory – all investment is predicated on paying for dollars of income. You pay so and so much for secure dollars of income (a treasury bill), and you may pay more for the opportunity to have an investment in something that may generate 100x that amount in 5 years. Right? By the way – the NYT published this fantastic read about how Silicon Valley is “trying out profitability” now. It’s what got me thinking of this whole thing, aside from the WeWork debacle, which I’ve followed with as much interest as any self-respecting Silicon Valley based investor.
Anyhow, the argument that a business cannot expect to lose money forever and still go public and receive investor dollars is sound. It’s true, that model does break down eventually. If you’re simply unprofitable forever, eventually people won’t give you money. You’re not actually making money! So therefore, what future dollar of income am I paying for? Where is the cash flow stream that was foretold?
I think a better question is – at what point does profitability (aka good margins) need to kick in? The mantra in venture capital circles has been the quest for scale (cue Masters of Scale, which by the way is a fantastic podcast). Is that the right way to think about it?
To try to answer this, I like constructing straw men. They make it easier to think about these issues (sometimes). So, let’s take this example – you have two businesses. And here’s an important point / question – are they software businesses, or are they some fancy disruption of an old-line industry (like WeWork) that require heavy capital expenditure for growth? It’s a super important point. Why?
This is a crucial point – your next sale of a unit of software doesn’t cost you more to sell it. The software is made. Yes, there’s COGS and all that fancy stuff (marketing, sales, customer service, etc.) but like – that piece of software doesn’t have a huge installation cost. By contrast, every expanding unit of WeWork’s empire does in fact require capital expenditure to grow. Opening a new building is enormously expensive. Now, I might argue that once a WeWork location is up and running you could expect it to generate nice income over time, though in fact the data does seem to contra-indicate this (shocking statistic – the costs of operating already opened offices for WeWork comprised 80% of revenue for the first half of 2019 [which is itself down from 99% in 2016]).
But whatever – this is beside the point (sort of). You have two businesses. Identical lines of business, and one has an obsessive focus on staying in the black and maintaining high profitability margins, and the other says damn the torpedoes and invests heavily in growth, marketing, basically paying for their growth. Your first business is going to be nice and profitable, but is that the goal? Here’s the thing – investors are in this game for equity growth, right? Like, if they wanted yield / profitability, they should just buy real estate. Real estate, by the way, exhibits equity growth. But as we know, the potential for astronomical equity growth / returns in venture capital trumps most other asset classes.
And how do you secure “huge equity growth”? Equity growth should be a direct function of growth in revenue / income, or the expected future growth in income. Because, at the end of the day, you are paying for expected income (as I said in the first paragraph). So, the fundamental duty of a business is to increase its income. And oftentimes (I would say most of the time), growth comes as a result of investment in sales, marketing and customer support. This requires money. This may even require a negative margin for a time, as you scale.
Here’s what I think is a crucial point. Let’s say you buy yourself an apartment building. It generates a very healthy 10% return per year on your cash. That’s great! Here’s the deal – an apartment building is going to sit there and make you money (most of the time) and isn’t too preoccupied with “competition”, or “brand”. I know, I know – new construction, meth labs, etc., can happen to a property – but you get the point. By contrast, a business that “sits still” is probably going to get killed. Literally. There are always competitors (if it’s a good space to be in), and those competitors are very much interested in killing you.
All of which means – it’s exceedingly dangerous to go the slow way. Let’s return to our two businesses. One invests in growth at all costs, and scales rapidly across the country. The other takes the slow approach, makes sure its operating margins stay nice and healthy, prints a profit. But the “slow road” is slow for a reason – in order to expand your business, you need money. Perhaps you need to sacrifice margins right now to stay ahead of your competitor (i.e. you need to advertise and invest in sales people as an up-front cost that you hope to recoup down the line in “scale”).
In three years’ time, business A has a healthy, profitable business but has not been able to invest in growth. By contrast, Business B has what I’d term an unhealthy-looking margins but has achieved scale (define this however you like). At this point, I would prefer to be Business B. Why? Presuming the executives are on top of their game and have made this growth decision as a conscious decision, they should have (and should always have) a plan for scaling this back and improving margins. More importantly – what does scale buy you?
I’d argue scale buys you three things. First – you have recognition as being a major, national player. I would argue this is valuable for a variety of reasons, but most important is that companies (or people) like to do business with companies that other people do business with. Second – you have customers. You have customers in place, which means that your competitor, if they want to displace you, have to fight you for it. As anybody can tell you, competition is for suckers – I’d rather dominate, and not get down in the trenches with people. If you’re the major player, your opponents are playing catch-up and having to do the equivalent of “assaulting fortified positions”. I’d rather be in the fortified position, personally. Third – and I think most important – you have data. You have the customers; therefore, you have the data and the market feedback, which if you’re doing your job should be turning into a better product, a more attuned product, a product that is more and more aligned with what your customers want and need.
So, in other words, raising heavy capital and investing heavily in growth can and does make sense to me. I think it has made sense for some time. The problem is this; the idea itself has been abused a bit. Hear me out. I think that the decision to grow at all costs has been blurred into growing fundamentally unprofitable businesses. What does “fundamentally unprofitable” mean? It means “bad business models”, backed by a lot of investor money, growing endlessly but never turning a profit.
If you’ve read this blog for any time, you’ll know that I don’t really believe in black and white positions. Everything is nuanced. My concern is, in general, I think people like to think in absolutes. Profit is good! Negative unit economics and ravenous growth fueled by investor money is bad! But that’s a bit too simplistic for my taste.
As the master of your business, a founder / CEO, or the Board Members, should really understand the levers they are pulling. Perhaps growth for scale makes sense right now. There had better be some serious analysis and data behind the decision making. I’d hesitate to pay for growth via advertising, if it doesn’t seem sustainable. There had better be some hard data behind why you’re going this route, and how you think you can turn that corner. I’d want to understand that. But I also would want a company to really prioritize growth and scale for the aforementioned benefits, rather than sit plump and happy, ready to be killed by a more aggressive and funded competitor. This isn’t a real estate investment, after all, but an equity investment that requires investment and compounded growth to hit a goal.
Trouble has sprung up from two different areas. First of all – scale at all costs, with no mind for how to turn that corner, leads to a business that needs to constantly be sucking in capital just to operate. Not just to grow, but to operate. Look @ that WeWork number I quoted – how much money is going just to “operate” already up and running stores? I don’t see how that is sustainable. It’s not a conscious decision to push for growth, it’s literally an unprofitable business (from what I understand). Second is valuations. And this has been the place where the real bloodbath is happening.
Valuations (as I said in a previous post) are not scientific. Especially in the early stage, where it’s more like magic – and somehow everybody gets a valuation of $10 million. However, the recent and notable examples of valuations being way off the mark have mostly been driven to astronomical levels in the late stage. This is a stage I’d argue is more mathematically sound. By the time a business (like WeWork) generates revenue of $1.8 billion and massive losses, you should be able to value that business more successfully. The problem is that the private markets lack the discipline of public markets. A single investor (SoftBank) can value a company, whereas in the public market SoftBank is just one of literally hundreds of thousands of market participants ascribing a valuation to that company. And the reason the private markets have done this is either a) investors believe they can see the promised land coming, or b) they have gotten wrapped up in the hype of their company and forgotten that eventually that corner needs to be turned (or … said differently … a VC may be aware that the market is irrational, and yet if they aren’t in this deal they may cease to be solvent for now – i.e. LPs may not re-up in their next fund).
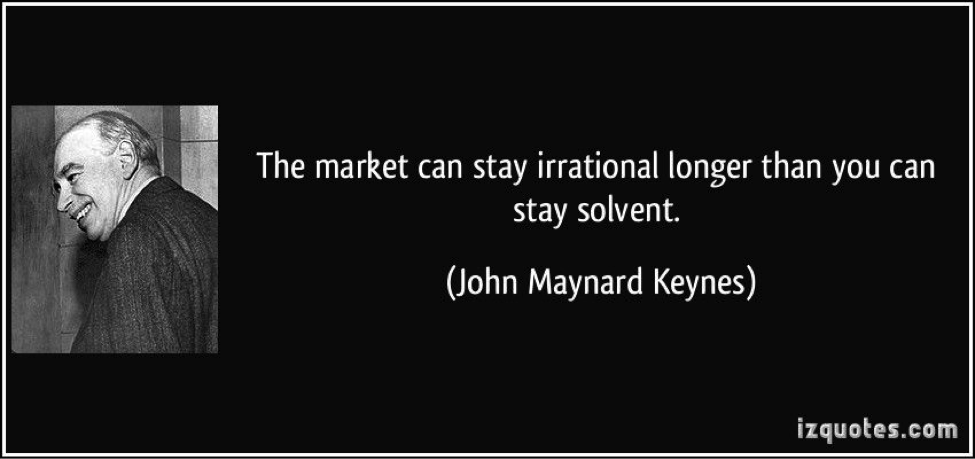
And so, what the market is saying right now is that fundamentally unprofitable businesses (specifically companies with terrible operating margins), where there is not a clear path to turning that corner, don’t deserve the valuations they’ve been getting. I don’t think they (the public markets) are wrong, by the way. All that I’m arguing is that the decision to scale your business with negative unit economics in order to achieve some goal, when coupled with a deep and rigorous understanding of your space and how you can turn a profit eventually, is not necessarily a bad idea. Everything with moderation. And the decision is not always in your hands – if your competitors are investing heavily in growth and seizing territories and making your life more difficult, are gaining an asymmetrical advantage through data and customer relationships, and building forts along the frontier – you might not have a choice anyways!
The fundamental purpose of a business is to make money, and you can’t forever grow with negative unit economics and a constant need for more cash to scale. There must be a turning point, and the founding team / strategy team should clearly enunciate how that will work and have some data behind why it will work. But it’s not so simple as make money and focus on profitability. Sometimes, if you don’t grow, even growth at a cost, you will die, and this growth might require periods of investment and negative returns. The market is extremely dynamic and volatile, and competitors are constantly coming after you. I’s the nature of capitalism. So be strategic!